Papa Johns Sales Slide Again in Q3 as Chain Launches ‘Unbox Better’ Plan
Papa Johns said North America comparable sales fell 8.3% in Q3 and revenue dropped 10.5% to $454.8 million as it launched a turnaround plan.
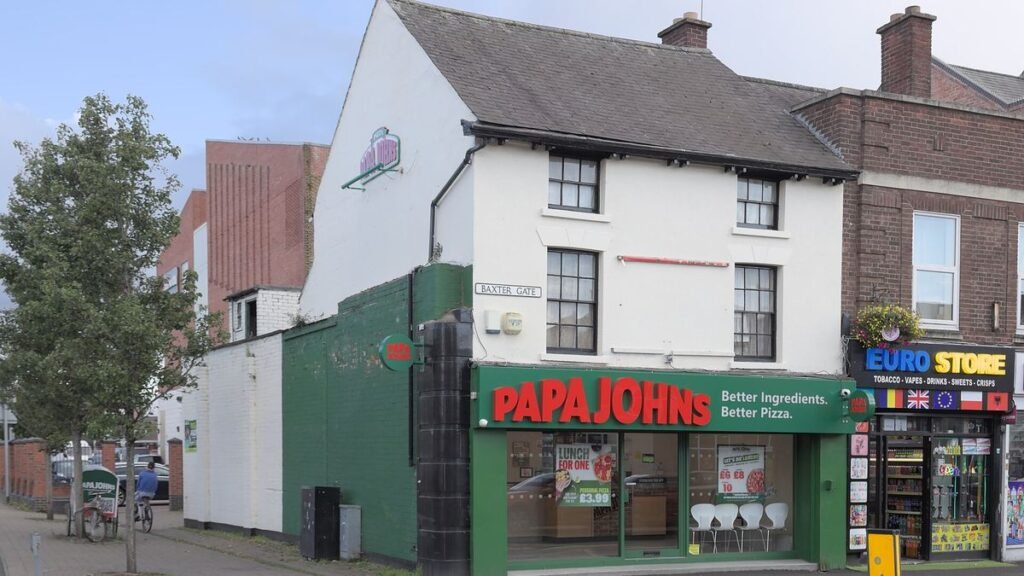
North American diners kept pulling back from Papa Johns in the third quarter, with comparable sales in the region down 8.3% from a year earlier, the pizza chain said Thursday as it unveiled a turnaround blueprint it calls “Unbox Better.”
Total revenue for the quarter ended Sept. 27 fell 10.5% to $454.8 million from $508.2 million, according to the company’s results release. Papa Johns attributed roughly $26 million of the drop to 113 company-owned restaurants it sold to franchisees after the third quarter of 2025, with the rest tied to weaker sales in North America. Yahoo Finance reported that analysts had expected revenue of about $459.8 million.
Net income slipped to $3.3 million from $4.5 million, or 9 cents a diluted share versus 13 cents. Adjusted earnings were 16 cents a share, down from 32 cents, and adjusted EBITDA fell to $38.1 million from $47.8 million.
Where sales fell
Comparable sales at domestic company-owned restaurants declined 7.5%, while North American franchised locations fell 8.5%. International comparable sales slipped 1.8%. Global system-wide restaurant sales, which include franchise stores, dropped 5.6% to $1.15 billion, excluding currency effects.
Nation’s Restaurant News noted that the North America figure matched the second quarter’s 8.3% decline and marked the ninth negative quarter in the past 10. The chain opened 47 restaurants during the period, 11 of them in North America, and ended the quarter with 5,969 locations in 51 countries and territories.
Chief Executive Todd Penegor told Yahoo Finance the quarter was “softer than we would have anticipated,” citing a tough pizza category and customers shifting toward protein-heavy, chicken and Mexican options.
Franchisee fees and the turnaround blueprint
Penegor said in the release that Unbox Better rests on two priorities: giving customers more reasons to choose Papa Johns and making sure restaurants consistently deliver on what the brand promises. The plan pairs product improvements and in-restaurant training with a new marketing setup.
Under that setup, franchisee contributions to the national advertising fund will drop to 5% from 6%, while a 2% local marketing contribution returns, according to Nation’s Restaurant News. Penegor told the trade publication that 98.5% of the franchise system voted in favor. The company is also adding 100 basis points of commissary margin support for franchisees and trimming technology fees by another 25 basis points.
A new point-of-sale system is expected to be fully deployed across the system by the end of 2027, the trade publication reported. Next week, the chain plans a “Bounceback” campaign offering customers a $5 incentive for submitting photos of their pizza as product feedback.
Full-year forecast trimmed
Papa Johns now expects 2026 adjusted EBITDA of about $175 million, below its earlier range of $180 million to $190 million. It forecast North America comparable sales down about 8% for the year, compared with its previous view of a 6% to 8% decline, and global system-wide sales down about 5%, versus a prior 2% to 4% decline. The company kept its outlook for 40 to 50 North American openings and 180 to 220 international openings.
Free cash flow for the first nine months of the year totaled $19.2 million, down from $59.2 million a year earlier, which the company linked partly to transformation payments and the timing of marketing fund and compensation payments. Yahoo Finance noted the stock had lost roughly half its value this year before Thursday’s report.
Sources: Papa John’s International (third-quarter 2026 results), Nation’s Restaurant News, Yahoo Finance
Get the BURN VOC Briefing
Top US news in your inbox. Free.
This story is published by BURN VOC under its newsroom byline and follows our editorial standards. Sources are named in the story. To report an error, email news@burnvoc.com. Editorial Standards · Corrections · About BURN VOC